David Hay — Friday POW!: Medtronic (MDT)
"The market's mental model is the 2021 version of Medtronic — a slow-growth conglomerate with an above-market dividend. The actual business today is in the middle of one of the most significant product-cycle accelerations in its history."
One-line take: The weekly "POW!" pick is Medtronic (MDT) — the de-rated MedTech giant at 13.6× forward earnings (peers 22–28×) just as four growth platforms inflect at once (Affera pulsed-field ablation +78%, Hugo surgical robotics, AiBLE spinal AI, Symplicity renal denervation) — a second straight healthcare pick, explicitly framed as part of a broad rotation into an undervalued sector. Data in the post as of 6/10/26. The closing portfolio tables (now titled "Buys" and "Holds, Trims, Sells") again drive portfolio.json.
1. Stocks & names mentioned
| Ticker | Name | Research | View | What he said | At |
|---|
| MDT | Medtronic | QT · SA · STK · FA | Positive | Pick of the Week — "we recommend a buy." Strongest top line in 10 years (FY26 revenue $36.4B, +8.4% reported / +5.8% organic; Q4 +6.6% organic) with four platforms inflecting at once (Affera PFA +78% global / +124% US with 8 pts of US share in one quarter, Hugo robotics, AiBLE spinal AI, Symplicity renal denervation) at 13.6× forward EPS vs peers at 22–28×. 12-month PT $103 probability-weighted (17× on FY27 EPS $5.95; 28% upside), 3-yr bull $130–145, bear case ~flat plus the 2.76% dividend. | read |
| BSX | Boston Scientific | QT · SA · STK · FA | Neutral | The benchmark peer that "quietly ate Medtronic's lunch" — trades at 28× and is still growing materially faster in many of the same markets; if that gap persists MDT may deserve a higher multiple, but not the peer-level valuation bulls expect. | read |
| ABT | Abbott Laboratories | QT · SA · STK · FA | Neutral | The other peer that took MDT's share through the 2021–24 drift — now the multiple comp at 22× forward earnings (the 20× ladder rung "approaches the multiple that peers Abbott and Boston Scientific command"). | read |
| ISRG | Intuitive Surgical | QT · SA · STK · FA | Neutral | The Hugo analogy and the Hugo risk in one: Hugo sits "precisely where Intuitive Surgical stood in 2005 before it built a $130 billion market cap" — but da Vinci's installed-base, clinical-evidence and ecosystem advantages are substantial and actively defended. | read |
| JNJ | Johnson & Johnson | QT · SA · STK · FA | Neutral | Passing mention in the Hugo bear case — J&J "is also competing aggressively" in surgical robotics alongside Intuitive. | read |
The post's closing Buys (43 lots) and Holds, Trims, Sells (54 lots) tables — the full Haymaker portfolio — are transcribed at the end of transcript.txt (image tables saved beside it) and reconciled into david-hay/portfolio.json. Week-over-week changes: MDT added as a Strong Buy (no cost basis yet), DGX now an actual lot (cost $200.29, B), FANG moved from Trims/Holds to the Buys list, the promised NOW de-dup happened (H/T only), USO's duplicate Buy lot dropped (Holds only), and IBM was cut to S (Sell) — the first Sell rating, matching the list's new "Holds, Trims, Sells" title.
2. Talking points
Back-to-back healthcare — a sector rotation call
- After historically featuring few healthcare names, this is the second healthcare POW in a row (after DGX): the stock is attractive on its own, but it's "also a recognition that healthcare as a whole looks undervalued and we're seeing a broad rotation into the space."
The setup — five frustrating years, now the wrong gameplan
- 2021–24: MDT grew slower than peers, lost share, and drifted $120 → $74 while Boston Scientific and Abbott "quietly ate its lunch" — the market settled on "legacy MedTech giant, too bureaucratic to innovate, nice dividend."
- FY2026 broke the pattern: $36.4B revenue, +8.4% reported / +5.8% organic — the strongest top line in 10 years, the product of three years of portfolio rationalization and pipeline investment "invisible to investors focused on the legacy narrative."
- BTIG upgraded to Buy from Neutral this week on consistent organic growth — read as "the beginning, not the end, of a re-rating cycle that could have years to run."
The re-rating math
- 13.6× forward earnings on FY27 guidance midpoint ($5.95) vs BSX 28×, ABT 22×, sector ~20× — a gap earned by years of skepticism but no longer justified by the numbers (Q4 +6.6% organic; FY27 guided 6.75–7.25%).
- Stage one — 13.6× → 17× on $5.95 — produces a ~$101 stock and "requires nothing more than the market applying a below-peer multiple to a company now growing in line with peers."
The four growth platforms
- Affera PFA — pulsed field ablation, possibly the biggest AFib advance in two decades: +78% global / +124% US in Q4, 8 pts of US share in one quarter; lower procedure time and skill dependency open community hospitals traditional ablation never reached.
- Hugo robotics — procedure volumes growing 2–3× the market; priced as a money-losing startup but really "at the inflection between investment and returns, precisely where Intuitive Surgical stood in 2005"; MDT's hospital relationships are a distribution edge no pure-play can copy.
- AiBLE spinal ecosystem — Mazor robotics + StealthStation navigation + O-arm imaging + UNiD AI planning in one workflow; Stealth AXiS cleared FDA in Feb-2026; installed base generates recurring per-procedure revenue — "physical AI in its most commercially mature form."
- Symplicity Spyral — renal denervation annualizing $100M with volumes more than doubling since Medicare reimbursement; 1.28B people globally have hypertension and a meaningful slice can't control it with pills.
Valuation — the de-rating and the ladder
- P/E melted from ~25× to 13.6× over five years ("most utilities sell for a higher multiple") — deserved, since earnings and sales flatlined for a decade; the saved 10-yr P/S + P/E chart shows the full de-rating.
- The ladder: 17× → $101 (+25%); 20× → $119 (approaching ABT/BSX); 22× → $131 (a MedTech growth premium). Base case: 13.6× → 17× over 12 months as two-three FY27 prints prove FY26 wasn't a fluke → $103 with a 3.57% dividend yield "providing return while you wait."
- Three-year bull (Hugo scales, Affera cements leadership): $130–145, a 60–80% total return. Bear at 13× (tariffs bite, cardio growth mean-reverts): ~$77, roughly flat before the dividend.
Technicals — a base, not a breakout
- The 2021 downtrend appears over (arguably since 2023); the stock has bounced in a 70–100 band and held ~$70 support for several years — "a solid base" that improving fundamentals could turn into a launch pad back toward the S&P's ~21 average P/E.
Arguing the other side
- BSX is still the benchmark and growing materially faster; Goldman Sachs stayed Neutral ($83 target) asking whether the growth is durable or front-loaded launch effect that normalizes as comps toughen — where does Affera's 78% settle once first-wave adopters are captured?
- Hugo is still money-losing with an uncertain path to profitability, against Intuitive actively defending da Vinci and J&J competing aggressively.
The bottom line + the portfolio
- "What are we buying here?" — strongest revenue growth in a decade, four billion-dollar platforms inflecting, 13.6× vs peers 22–28×; downside limited, upside "surprisingly lucrative." Buy recommended.
- The closing book: 43 Buy lots / 54 Hold-Trim-Sell lots. MDT enters as SB; DGX gets its lot ($200.29); FANG promoted to Buys; NOW de-duped to H/T; USO's Buy lot dropped; IBM cut to S — the first Sell.
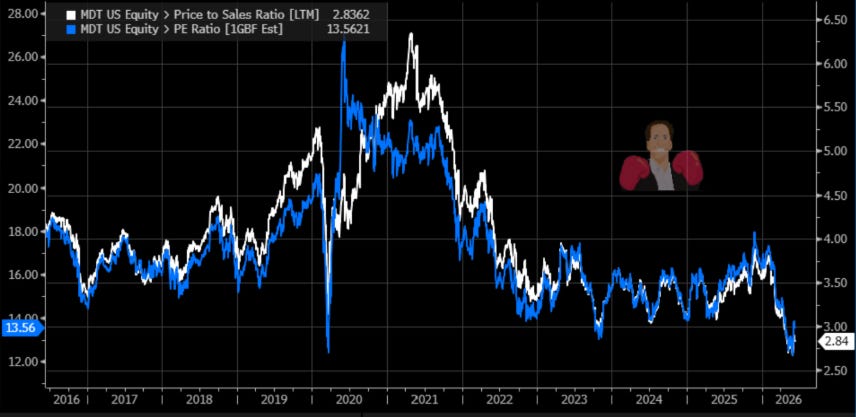
The de-rating: 10 years of MDT price/sales (white, 2.84) and forward P/E (blue, 13.56) — from ~25× earnings in 2021 to below most utilities (Bloomberg, via the post).
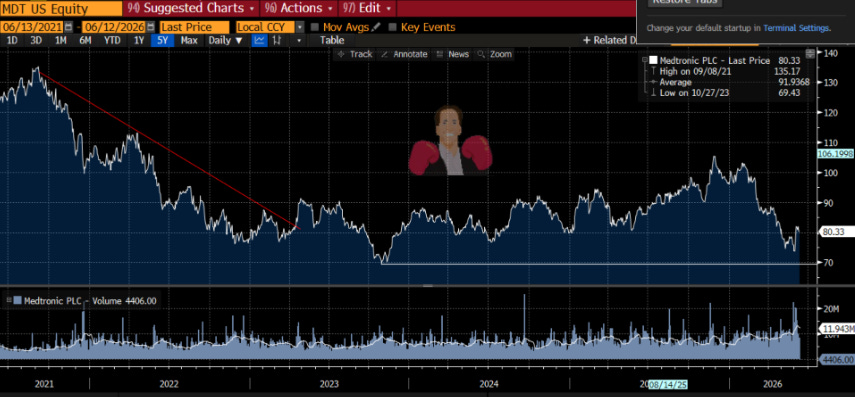
The base: five years of MDT — the 2021 downtrend line (red) is broken, and ~$70 support has held for several years; last $80.33 (Bloomberg, via the post).
3. In plain English
MDT — Medtronic Positive
Medtronic is one of the world's biggest medical-device companies — pacemakers, defibrillators (it's the world's leading maker), insulin pumps, surgical tools. For five years it was the industry's disappointment: growing slower than rivals Boston Scientific and Abbott, losing market share, and falling from $120 to the $70s, so the market now prices it like a sleepy dividend stock at 13.6 times next year's earnings while its peers fetch 22–28 times.
Haymaker's argument is that the company quietly fixed itself and the market hasn't noticed. Its newest fiscal year showed the fastest sales growth in a decade, driven by four young product lines hitting their stride at once: a new heart-rhythm treatment (pulsed field ablation) growing 78% and taking share fast, a surgical robot (Hugo) at the same stage Intuitive Surgical was before it became a giant, an AI-guided spinal-surgery system, and a one-time outpatient procedure that durably lowers blood pressure for people whose hypertension pills don't work. If the market merely lifts the stock to a still-below-peer multiple as the growth proves durable, that's roughly $103 within a year (28% upside); the bull case is $130–145 over three years. And if it's wrong, the bear case is roughly today's price — while a 2.76% dividend pays you to wait. That limited-downside / lucrative-upside shape is exactly what they say they look for, and MDT entered the Haymaker Buys list this week as a Strong Buy.
Summary derived from the paid Haymaker newsletter (text in transcript.txt) for personal study. Not investment advice. © Haymaker / David Hay for source material.