| Ticker | Name | Research | View | What he said | At |
|---|---|---|---|---|---|
| AGI | Alamos Gold | QT · SA · STK · FA | Positive | ★ Today's rating change — upgraded to Strong Buy (SB) on the published Buy List, delivering on the July-27 line "before long we may bump it up to a Strong Buy." The lot is dated 07/11/2022 at a $7.06 cost, marked $28.23 (+299.86%). No fresh prose — the change is stated by the blue-highlighted table cell; the July-27 underwrite (10.4× trailing, under 10× 2027 consensus, a fading Young-Davidson earthquake, central-bank bullion buying, contrarian retail negativity) is unchanged. | read ↗ |
| BOLSY | Brasil Bolsa Balcão (B3, ADR) | QT · SA | Positive | ★ Today's rating change — upgraded to Strong Buy (SB) on the Buy List. Lot dated 07/13/2026 at $9.85, marked $9.21 (−6.50%) — i.e. the upgrade comes on a name that is down since the July-13 "amped up" reiteration, consistent with Haymaker's habit of raising the rating as the price falls against an intact thesis (Brazil's monopoly exchange at trough P/S with a ~5% dividend, into an expected collapse in record-high Brazilian real rates). | read ↗ |
| CRH | CRH plc (building materials) | QT · SA · STK · FA | Positive | ★ Today's rating change — moved off Holds/Trims and back onto the Buy List, rated B, on both lots (01/29/2024 @ $73.23, +33.27%; 04/28/2025 @ $98.51, −0.93%; marked $97.59). A re-promotion of the aggregates/building-materials name into the reindustrialization-and-hard-assets leg of the book, stated by the table rather than argued in prose this week. | read ↗ |
| EQT | EQT Corporation | QT · SA · STK · FA | Positive | ★ Today's rating change — upgraded to Strong Buy (SB) on both lots (03/20/2026 @ $64.96, −17.75%; 04/20/26 @ $57.00, −6.26%; marked $53.43). America's largest vertically-integrated Appalachian gas producer — unhedged for 2026, "a pure, unlevered call option on the current gas price environment" — gets its highest rating after an ~18% drawdown from the March pick, the same buy-it-lower discipline applied to BOLSY this week. | read ↗ |
| PSLV | Sprott Physical Silver Trust | QT · SA · STK · FA | Positive | ★ Today's rating change — upgraded to Strong Buy (SB) on the Buy List (lot 08/26/2024 @ $9.82, marked $18.82, +91.65%) — up from the B it was assigned on July 20. The physical-silver vehicle behind the standing "gradually accumulate silver and the miners" stance (constrained supply against munitions / AI-data-center / grid demand pushing the market into a pronounced deficit). | read ↗ |
| YACAF | Yancoal Australia (ADR) | QT · SA · STK | Positive | ★ Today's rating change — upgraded to Strong Buy (SB) (lot 04/09/2026 @ $5.20, marked $3.81, −26.73%) — the deepest drawdown on the Buy List gets the top rating, hardening the July-20/24 "time is of the essence" adds. The trapped-LNG substitution thesis (Indonesian export cuts into an Asian LNG shortage) is unchanged; the table simply raises the conviction. | read ↗ |
| ACN | Accenture | QT · SA · STK · FA | Neutral | ★ Today's rating change — moved off the Buy List onto Holds/Trims, rated H (lot 05/08/2026 @ $178.31, marked $167.71, −5.94%). The July-6 "Hold / Accumulate" language is now formalized as a plain Hold on the table — the position stays, but Accenture is no longer a name Haymaker is telling readers to buy. Consistent with the same day's instruction to raise cash in expensive securities. | read ↗ |
| MTB | M&T Bank | QT · SA · STK · FA | Neutral | ★ Today's rating change — moved off the Buy List onto Holds/Trims, rated H (lot 09/23/2025 @ $187.34, marked $248.58, +32.69%). Notable for its timing: it lands three days after the July-31 POW! made KRE — the equal-weighted regional-bank basket — a rated Buy, so the single-name regional winner is downgraded to a hold while the diversified vehicle carries the sector call. | read ↗ |
| TRV | Travelers | QT · SA · STK · FA | Neutral | ★ Today's rating change — moved off the Buy List onto Holds/Trims, rated H (lot 6/26/2026 @ $327.37, marked $373.24, +14.01%). The June-26 POW! quality-compounder pick is up ~14% in five weeks and is now a hold rather than a buy — the "raise cash in richly valued securities" instruction applied to a winner that has run to the top of its re-rating range. | read ↗ |
| PBR | Petrobras (ADR) | QT · SA · STK · FA | Neutral | Now sits on Holds/Trims rated H/T with a trim dated 08/03/26 — today (lot 12/31/2025 @ $11.85, marked $19.05, +60.76%). Petrobras has run ~61% from cost and comes off the Buy List into an explicit trim on the same day Haymaker tells readers to raise cash — profit-taking on the deep-value Brazil oil major, not an exit. | read ↗ |
| AEM | Agnico Eagle Mines | QT · SA · STK · FA | Neutral | Housekeeping, explicitly flagged: the trim date is corrected from 07/20/2026 to 07/13/2026. The gold miner stays on Holds/Trims rated H (lot 02/10/2025 @ $97.04, marked $146.76, +51.24%) — i.e. the trim was executed a week earlier than the published table had shown, a record correction rather than a fresh stance. | read ↗ |
| SPCX | SpaceX | QT · SA · STK · FA | Negative | The exhibit for "rampant speculative behavior." At $225/share — up ~70% from the $135 IPO price — the valuation was "nearly $2½ trillion… almost 70 times sales." And then: "showing how quickly bubble-like valuations can reverse, its market cap is down to $1.4 trillion." Cited to rebut the idea that today lacks the 1999 precondition of extreme valuation plus speculation — the setup that let a rate spike deliver the "coup de grâce." Cautionary, not a short call. | read ↗ |
"View" is Haymaker's stance in this Portfolio Update. ★ marks the nine blue-highlighted cells on the published tables — that day's rating changes. SPCX is the only name argued in the prose (as the bubble exemplar); the rest are the table's dated actions. Not rowed: the Japanese yen — Haymaker reiterates the bullish yen call but, as on 2026-JUL-09, names no ETF or ticker, so it is logged as a macro/FX viewpoint rather than a security. Also not rowed: table reconciliations with no stated change this week (GDX / GDXJ now shown on the Buy List, CPRT and KRE newly listed after their POW! picks). Referenced only (not tickers): the 30-year US T-bond, the S&P 500, the Bank of Japan, the U.S. Treasury, Jay Powell, Paul Volcker and Y2K. Research: QT Qualtrim · SA Seeking Alpha · STK Stock Analysis.
A jargon-free note on why each name matters here. (Companion to the table above; renders on each name's consolidated page.)
Hay uses SpaceX as the poster child for how stretched this market got. After its IPO at $135 the stock ran to $225 — almost 70% higher — which valued the whole company at about $2.5 trillion. To put that in perspective, that was roughly 70 times its annual sales: you were paying seventy years of revenue (not profit — revenue) for the business. Then it fell apart fast; the company is now worth about $1.4 trillion, roughly a 45% haircut in weeks.
The point isn't really about rockets. Hay is answering people who say today's market can't crash like 2000 because things are different. His argument: the 1999-2000 bust needed two ingredients — sky-high valuations and wild speculation — and the sharp rise in long-term interest rates was just the match that lit them. SpaceX is his evidence that both ingredients are present again, and that when this kind of valuation unwinds it does so violently. Treat it as a warning about the whole speculative end of the market rather than a bet against the company.
Alamos is a mid-sized gold miner Haymaker bought back in 2022 and has ridden up nearly 300%. A week ago Hay put it back on his buy list at $29 — half its February peak — and said he might soon raise it to his top rating. This week he did: it is now a Strong Buy, his highest conviction level. Nothing new is argued; the July 27 case still stands (the stock is under 10 times next year's expected earnings, its reserves have nearly tripled in a decade, an earthquake at one mine is treated as a one-off, and central banks keep buying gold while ordinary investors have soured on miners — which he reads as a contrarian positive).
B3 is Brazil's stock exchange — the only one — so it collects a small toll on essentially every trade in the country. Haymaker owns it and this week raised it to Strong Buy, even though the position is down about 6.5% since he bought in mid-July. That is his usual pattern: when a business is doing fine but the share price falls, he raises the rating rather than lowering it. The underlying bet is that Brazil's extremely high interest rates come down sharply, which would spark a bull market in Brazilian shares — and more trading means more tolls for the exchange, which already pays about a 5% dividend.
CRH is one of the world's largest suppliers of the physical stuff construction runs on — cement, aggregates (crushed stone and sand), asphalt and ready-mix concrete — with a huge North American business rebuilding roads, bridges and industrial sites. Haymaker has held it for years; this week it moves from the "hold or trim" list back onto the buy list, on both of its lots. No fresh write-up accompanies the move, so read it as the building-materials name being re-promoted into the same hard-asset, reindustrialization side of the book that Hay keeps favouring over the AI complex.
EQT is America's biggest natural-gas producer in Appalachia, and it deliberately hasn't locked in ("hedged") the price it gets for its 2026 gas — so every dollar the gas price rises drops almost straight to its cash flow. That makes it, in Hay's phrase, a pure bet on the gas price. He first recommended it in March; the stock has since fallen roughly 18%, and rather than back away he has now raised both of his lots to Strong Buy. The logic is the standing one: US gas sells for a fraction of what the rest of the world pays, and AI data centres plus new export terminals are lining up to soak up the surplus.
PSLV is a simple way to own silver bullion: the fund holds real bars in a vault, so buying a share is close to owning the metal without storing it yourself. Haymaker bought it in 2024 at under $10 and it has nearly doubled. This week it goes from a plain Buy to a Strong Buy. The reasoning behind the position hasn't changed: silver supply is tight while demand from munitions, electrical grids and AI data centres is rising, pushing the market from surplus into shortage — and after silver's crash from ~$120 to ~$58 earlier this year, sentiment is washed out, which he treats as the time to accumulate rather than avoid.
Yancoal mines thermal coal in Australia — the kind burned in power stations. It has been Haymaker's worst recent call, down about 27% from where he bought it. He is not retreating: this week it is upgraded to Strong Buy, the deepest loser on his buy list getting his highest rating. The bet is a substitution one. Power plants across Asia can burn either coal or liquefied natural gas (LNG); with LNG shipments still snarled in the Persian Gulf and Indonesia — the largest coal exporter — cutting shipments, buyers have to fall back on coal, which should lift its price. He has said repeatedly that "time is of the essence" on adding here.
Accenture is the world's largest technology-consulting firm — the people companies hire to actually install and run the software they buy. Haymaker bought it in May as a supposed "AI victim" whose numbers said otherwise. This week it comes off the buy list onto the hold-or-trim list, rated simply Hold. In plain terms: keep what you own, stop adding. It's a small step down from the "hold and accumulate patiently" language of early July, and it fits the same day's blanket instruction to raise cash in richly valued names.
M&T is a large US regional bank Haymaker bought last September; it's up about 33%. This week it is demoted from buy to Hold. The timing is the interesting part — three days earlier he made a rated Buy of KRE, the fund that owns roughly 150 regional banks at once. So the sector call is being expressed through the diversified basket, while the individual bank that has already run 33% is downgraded to a hold. That's a deliberate swap of single-company risk for spread-out sector exposure, not a change of mind about regional banks.
Travelers is a big property-and-casualty insurer and was Haymaker's Pick of the Week on June 26 as a quality compounder. Five weeks later it's up about 14% and gets moved off the buy list to Hold. The June case (an insurer earning excellent returns, sitting on a $106 billion bond portfolio that pays more as rates rise, at a cheaper multiple than its peers) hasn't been withdrawn — the stock has simply covered a good chunk of the re-rating he was playing for. Combined with this week's "raise cash in expensive securities" message, the read is: keep it, don't buy more here.
Petrobras is Brazil's state-controlled oil giant and a long-time Haymaker favourite, bought at the end of 2025 and now up about 61%. This week it moves onto the hold-or-trim list with a trim actually dated today — meaning some of the position is being sold to lock in the gain. It's the "raise cash" instruction applied to his own book rather than a change in the oil view (he still argues crude is far too cheap and that oil-producer shares are the place to be). Read it as banking part of a big winner, not walking away.
Agnico Eagle is a large, high-quality gold miner Haymaker has held since early 2025, up about 51%. Nothing changes in the stance this week — it stays a hold — but the published table is corrected: the date on which he trimmed the position was wrong, and moves from July 20 to July 13, 2026. Worth recording only because the tables double as the newsletter's public scorecard, and the trim date determines the price at which the sale is credited.
Reproduced from the post; blue-highlighted cells are that day's rating changes. Transcribed in full in the appendix of transcript.txt.
Buy List
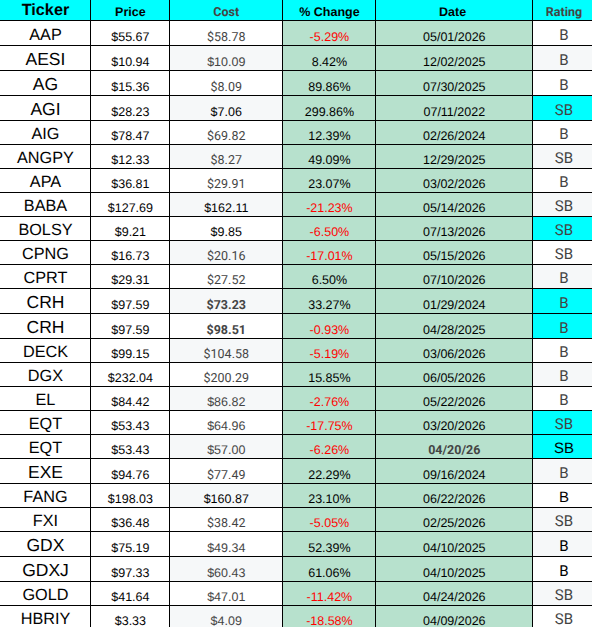
Buy List (AAP–HBRIY). Blue: AGI → SB, BOLSY → SB, CRH → B (both lots), EQT → SB (both lots).
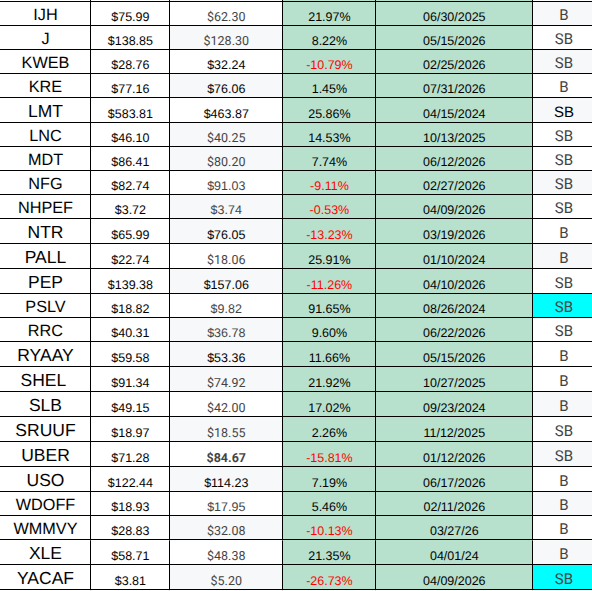
Buy List (IJH–YACAF). Blue: PSLV → SB, YACAF → SB. Also newly listed here: KRE (the Jul-31 POW! pick) at a $76.06 cost.
Holds / Trims
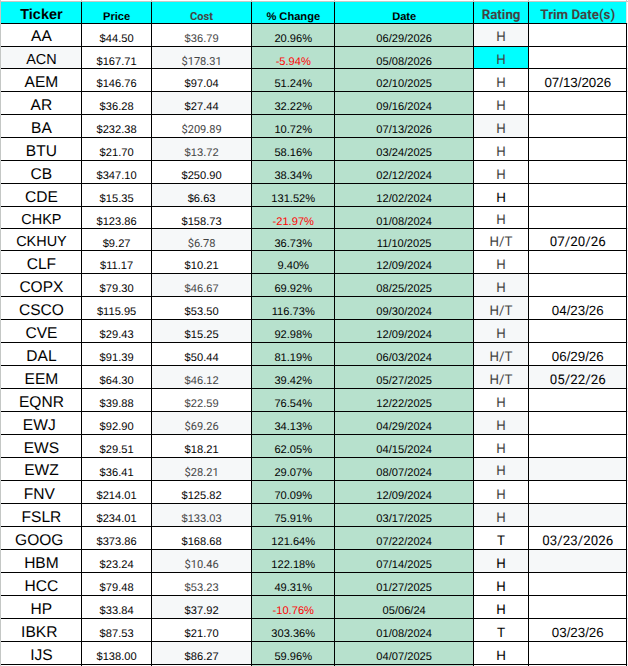
Holds/Trims (AA–IJS). Blue: ACN → H. Note the corrected AEM trim date, 07/13/2026 (was 07/20/2026).
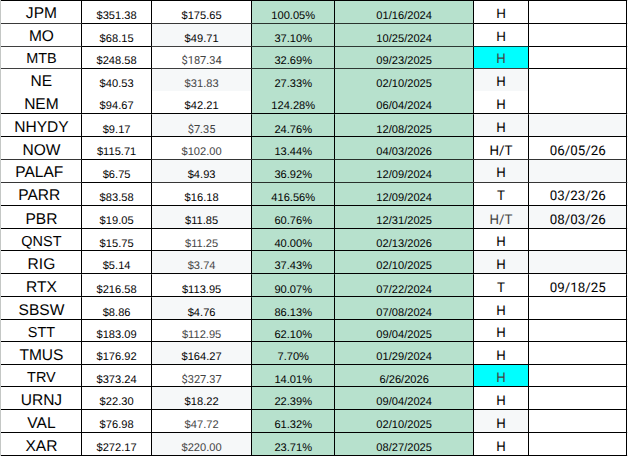
Holds/Trims (JPM–XAR). Blue: MTB → H, TRV → H. PBR carries a trim dated 08/03/26 — today.
Sells
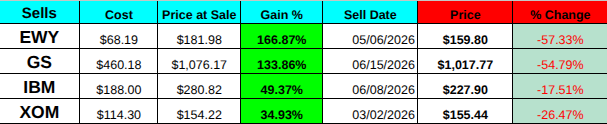
Sells — unchanged from July 20, but every name is now well below its exit price (EWY −57.3%, GS −54.8%, IBM −17.5%, XOM −26.5% since sale).
Summary derived from the paid Haymaker newsletter (text in transcript.txt; portfolio tables reproduced as hay1–hay5.png) for personal study. Not investment advice. © Haymaker / David Hay for source material.